
Does Homeowners Insurance Cover a Rented ADU in California?
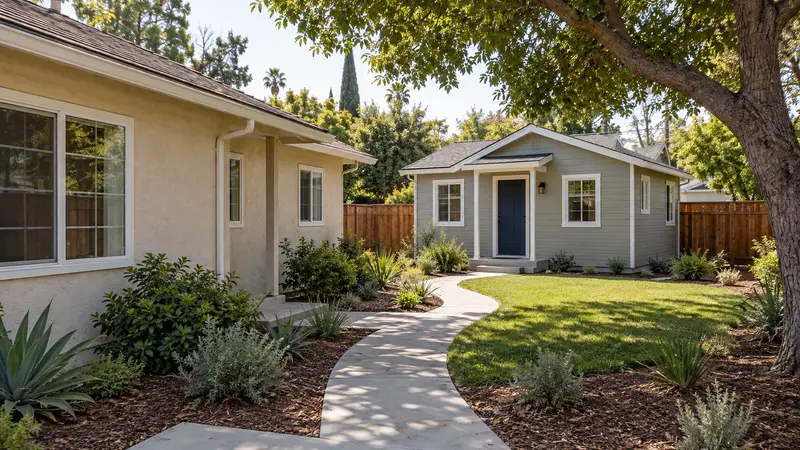
You finish a backyard unit in Tarzana, list it for rent, and wonder whether your home insurance already covers the new building. The words “homeowners policy” alone do not give you a dependable yes or no answer. ADU insurance in California depends on the property's layout, how the unit is used, the insurer's rules, and the policy you actually hold.
Tell your insurer or agent about the ADU before a tenant moves in, ideally while you are still planning it. Ask for written confirmation of how the structure and rental activity will be insured. If you are comparing options, start with home insurance for California properties.
Will Your Existing Homeowners Policy Cover the ADU?
Maybe, but do not assume the detached unit is insured just because the main house is. Some insurers may be able to address an ADU through the existing home policy and an endorsement. Others may require a different policy arrangement, especially when the unit is rented. Coverage can also differ for an attached conversion, a detached backyard home, a unit used by family, and a long term rental.
Start with two questions: Does this policy insure the ADU building, and does it allow the way I use it? Ask your agent to identify the coverage limit and deductible for the unit. The California Department of Insurance reminds consumers that their actual policy determines coverage. A general description of homeowners insurance cannot settle this for your property.
Four Coverage Questions to Settle Before You Rent It Out
1. What would pay to repair or rebuild the ADU?
The cost to rebuild a finished unit can differ from what you spent converting a garage or adding square footage. Tell the insurer when construction is complete and share details such as size, construction type, permits, and intended occupancy. Ask whether the ADU has its own dwelling limit, falls under other structures coverage, or needs a different arrangement. Do not guess based on the home's market value.
2. How does liability work when a tenant or guest is injured?
A rented unit introduces questions about stairs, walkways, gates, and shared spaces. Ask what liability coverage applies to the rental exposure, what limit you have, and whether a landlord or umbrella option is appropriate. Our Northridge landlord insurance guide explains the broader difference between insuring a home you live in and a property you rent out.
3. What happens to rent if the unit cannot be occupied?
If a covered loss makes the ADU unlivable, you may lose rent while repairs are made. Ask whether the proposed policy includes loss of rents or fair rental value coverage, when it applies, and what time or dollar limits apply. Do not confuse the homeowner's additional living expense coverage with protection for rental income. They answer different questions.
4. Whose belongings are insured?
Your policy may address appliances or furnishings you own in the unit, subject to its terms. A tenant's clothes, laptop, and other belongings generally call for the tenant's own policy. If a prospective tenant asks about this, point them to renters insurance for their property and liability needs. The California Department of Insurance explains that a landlord does not insure a renter's personal property.
Tell Your Agent What You Are Building and How You Will Use It
For a useful coverage review, describe whether the ADU is attached or detached, whether it is finished or still under construction, who will live in it, and whether you plan to rent it for months at a time or offer short stays. Share the square footage and details about any kitchen, separate entrance, and shared utilities. Short term rentals can raise different underwriting questions, so do not describe one as an ordinary long term lease.
Construction is its own stage. Before work begins, ask how your current policy treats the project, materials, and changes to the dwelling, and what coverage your contractor carries. Once the ADU is finished, update the insurer again so the completed unit and its actual use are reflected in the coverage discussion.
What About Wildfire, Earthquake, and Flood?
Valley properties can face different exposures depending on location. Ask how the ADU is treated under any wildfire related property coverage and whether its rebuild value is included. Standard residential policies typically do not include earthquake or flood damage automatically, so discuss those risks separately instead of assuming an ADU follows the same terms as the main house. If the property is on the FAIR Plan, review what other coverage is needed for the rental exposure rather than assuming the FAIR Plan covers every cause of loss or liability. The OGI San Fernando Valley wildfire and home insurance guide provides useful context for that conversation.
Get the Coverage Question Answered Before the First Lease
An ADU might house a parent this year and a tenant next year. That change matters. Keep your agent updated when the unit's use changes, ask for an explanation of the limits and exclusions, and keep the updated policy documents. You should know what is insured before a loss occurs.
Planning to Rent an ADU in the San Fernando Valley?
Ask Online General Insurance to review your home and rental exposure. The Tarzana based team can compare available options for your property and explain what the quoted policy would cover.
Frequently Asked Questions
Do I need a separate policy for a rented ADU?
Not necessarily. The answer depends on the insurer, the property's details, and how the unit is rented. Ask whether an endorsement to your current policy is available or whether another policy is needed, and get the answer in writing.
Does my homeowners policy automatically cover a detached ADU?
Do not assume it does. Ask your insurer whether the detached unit is included, under what coverage section, at what limit, and whether rental use is allowed.
Does landlord insurance cover my tenant's furniture?
Generally, insurance arranged by the property owner covers the owner's interests, not the tenant's personal belongings. A tenant should look into a separate renters policy for their own items and liability.
Can I use the same coverage for a family member and a paying tenant?
The insurer may treat those uses differently. Tell your agent when occupancy changes and ask whether your existing coverage needs an update before a lease begins.
Will insurance replace rent after a covered fire?
Possibly, if loss of rents or fair rental value coverage is included and its conditions are met. Ask about the covered causes of loss, waiting period, limits, and how payments are calculated.
Should I update my policy while the ADU is under construction?
Yes. Tell your agent before construction starts and again when the unit is finished. Coverage for a construction project and coverage for a completed rental unit may involve different terms.